Conversation No. 010
The 100 Year Conversation
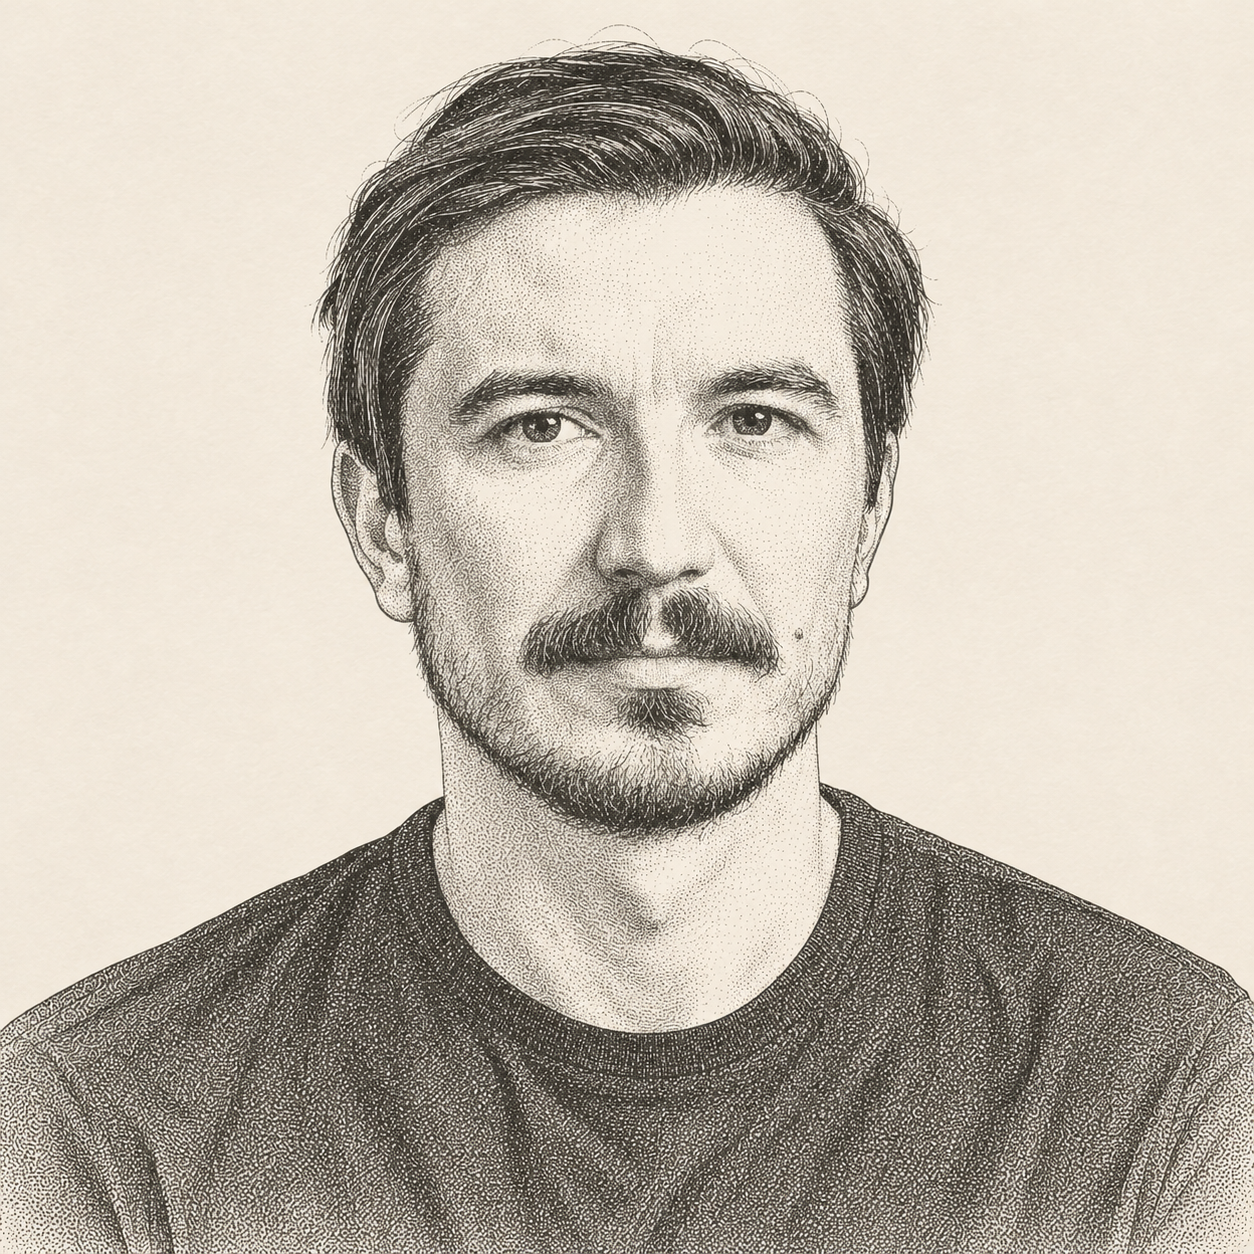
In Conversation with Vlad Tenev
Ownership, opportunity, and the ambition behind Robinhood.
In this conversation, Vlad Tenev reflects on his childhood, his early experiences in the stock market, and building Robinhood through periods of growth and crisis. He discusses ownership, parenting, math and financial markets, and how Harmonic brings him back to questions that interested him long before he became an entrepreneur.
I met up with Vlad for a walk in Palo Alto. Our conversation started in Bulgaria, where he was born and spent his first five years as the country emerged from communism. During the 1990s its economy fell apart. Banks failed and inflation went above 1,000 percent, wiping out people’s savings. His family left for the United States in 1992. Money was tight there too. Vlad learned to get by on his own early. He did well in school, especially in math, and by middle school he had a pretend stock portfolio on Yahoo Finance over dial-up. At twelve, he took the SAT through a program for gifted students, and his father offered him a deal: if he scored above 1300, he would put the same number of dollars into a real brokerage account. Vlad scored 1370.
His first account reminded me of my own. I started investing in eighth grade too, with money from my father. I was curious what Vlad remembered about the ups and downs of those first investments. Owning stock, he told me, felt like collecting. Shareholder materials arrived in the mail, and he could vote. I like to think about a portfolio that way too, and liked hearing Vlad describe that owner’s mindset, because Robinhood is so often discussed in terms of trading.
After high school, Vlad studied math at Stanford and UCLA, then began building software for financial firms with fellow Stanford alum Baiju Bhatt. Building tools for Wall Street showed them how cheap trading was for the big firms, and how expensive it was for everyone else. In 2013, they founded Robinhood to open the stock market to a wider audience, removing trading commissions and account minimums. The company now offers retirement accounts, cryptocurrency, and other financial services to nearly 29 million funded customers.
Harmonic, the AI company he co-founded in 2023, brings him back to math, building systems that reason through problems and formally verify the results. He’s been thinking about this since college. For this series about building institutions that last, I enjoyed talking to someone who thinks in decades and is still running his company day to day.
On Money and Scarcity
Gaurav Ahuja
You immigrated to the U.S. at the age of five. When you were nine, Bulgaria's banking system collapsed. I think a third of the banks failed. Hyperinflation destroyed the savings of the world that you'd grown up in before moving to the U.S.
I've always seen Robinhood as the story that begins with Occupy Wall Street and creating democratized access to equity trading. Is there a connection between the collapse of the Bulgarian financial system and your later interest in creating an equity brokerage?
Vlad Tenev
I think there were a lot of influences at that time. Finances and money were a huge part of my childhood. Bulgaria was going through the highest inflation in the world in 1997, exactly as you mentioned.
Even my last year in Bulgaria, 1991, was kind of the first year it got really bad. It wasn't three thousand percent inflation, but it was like 170 percent, right? We freaked out in the U.S. about nine percent, which was really bad. So imagine 170 percent.
Some of my early memories were of looking out the window of our apartment block in Varna, Bulgaria. We'd be checking out the line at the bodega where people in the neighborhood would go buy milk and eggs. We had a view of it from our window. I would tell my dad: oh, Dad, now's a good time to go. The line isn't around the block. Hopefully they're not sold out.
There were also rolling blackouts. There wasn't enough energy to go around, so they had these rolling blackouts every night, and we would just be huddled around the radio. The radio had batteries, and so that was kind of the entertainment.
We moved to America, where the structure of society felt much more stable. There were no rolling blackouts, and everything was cleaner, even though we were very poor at the beginning.
But my family's individual position was very fragile. It always felt like we were visa holders, kind of one step away from having to go back to Bulgaria. I was very, very aware of how much money we had, how ATMs worked, why you couldn't just get infinite amounts of cash from the ATM, how much things cost.
Then in 1997, when I was ten years old, I saw my grandparents' pensions evaporate. My grandfather was always thinking about how to store his wealth. He was a collector of copper cookware. He had this closet in their apartment, which was just full of copper pots and pans. That was where they custodied their assets. They just kept adding zeros to the currency. We’d come back to Bulgaria—a cheeseburger went from two leva to 2,000 leva.
We didn't have very much money of our own. But I think if my grandparents didn't have my parents funding them, they would have had a much more difficult time. The pensions were basically worthless.
On Learning to Invest
Gaurav Ahuja
When did you first become interested in investing?
Vlad Tenev
I became interested in investing around then, probably when I was ten or eleven. The dot-com boom was happening. I opened up a Yahoo Finance stock account—a fake-money portfolio—and created a portfolio of companies.
My parents had never done that. They'd never really done any investing on their own. I think they were pretty surprised when I was like, “Hey, look, my fake portfolio is doing pretty well.” They're like, “How do you know what a portfolio is? How do you know what a stock is?”
I was figuring this out on my dial-up connection. When I was, I think, twelve, I participated in CTY, a Johns Hopkins program where you take the SAT as a middle schooler. Depending on how you do, there are awards and things. If you do really well, you get to go to this camp, which was kind of prestigious, where you get to do one year of math in two weeks—like twelve hours a day of math. I did this two summers in a row.
My dad came up with this great idea to incentivize me. He said, “All right, if you get over a 1300 on your SAT, I will give you an equivalent amount in cash to invest in stocks.” That was pretty motivating to me. I ended up getting a 1370, and he opened up a brokerage account for me to start investing.
Gaurav Ahuja
You were getting exposed to the emotional ups and downs of investing much earlier than someone who starts in their twenties or thirties. What was that experience like?
Vlad Tenev
This was 1999, so I got to go through all the emotions on an accelerated basis. First, I made a lot of money. I bought stock in 3Com, which made the PalmPilot at the time. They later spun off Palm, and I learned about corporate mergers and reorganizations.
I also learned about bankruptcy. A lot of companies went bankrupt. I ended up losing a decent chunk of that portfolio, and I didn’t get back above even until 2009 or 2010.
Gaurav Ahuja
Were you putting real fundamental thought into these companies? You weren’t trying to read the latest headline and make a trade or follow stock tips online? You were trying to analyze companies as a twelve-year-old?
Vlad Tenev
It was a combination. We had this thesis that companies whose products my parents' employer used were going to be good companies. They were like: we're all using SAP. Maybe SAP would be a good company. That seemed reasonable at the time. So I bought some SAP shares.
I did have some less well-informed trades. The strategy that really didn't work out very well was: hey, on our way to the airport on the Dulles Corridor, there are all these new buildings coming up. Let's invest in some of those. Net2000 Communications, for example. I invested in that one. I think that one ended up being a zero. So I covered the wide breadth of fundamental and technical strategies.
Gaurav Ahuja
Do you think that you took to investing because it was a form of wealth creation while sitting behind your desk, and you came from a background that didn’t have a lot of wealth growing up? Was that the core of it?
Vlad Tenev
I think there were two aspects of it that appealed to me. One was obviously this idea that you could make money, right? And by being smarter and utilizing the mathematical skills and the quantitative skills, you could actually make a lot of money. That definitely appealed to me.
But then there was also this idea of the long-term ownership mindset, and maybe there are some similarities with being a collector. You could hold high-quality assets and kind of build up a collection, which I think your long-term portfolio is an example of.
It's almost like you're collecting art, you're collecting cars, you're collecting watches. But of course, not all people have the ability to do that. You could collect ownership of many companies, and that kind of becomes an asset that you own. It's sort of like a point of pride.
I remember when I got my 3Com Palm shareholder materials in the mail, and I actually felt like, “Oh, wow, I'm an owner of this company.” I can vote for it. And I read those materials. Even though you're pretty small, you feel a connection to that company and you care much more about it.
I'd say I take pride in what's in my portfolio. That's why I like investing in individual stocks.
An individual stock really allows you to build a portfolio and kind of curate it, which I think is very nice. It's these two things: the ownership of it and obviously the ability to make money.
On Motivation and Upbringing
Gaurav Ahuja
You were clearly motivated as a kid, long before Robinhood. You were getting good grades and going to summer camps that accelerated math. What drove you? Was there something you were trying to prove?
Vlad Tenev
I think it was probably a combination of things. At first, the motivation was just survival, right? My parents would sit me down and they'd say: look, your father's not making very much money. He's a graduate student. Our status as visa holders in this country is very fragile. I don't know if we're going to be able to pay for your college, so you're going to have to get a scholarship, which means you're going to have to get really good grades.
So I think my parents, from a pretty young age, really emphasized education and doing well in school.
But also, they were not home with me all the time. They both worked extremely hard. That meant I had to be autonomous. They weren't going to sit with me and do my homework. I was on my own and had to figure it out. I think that ended up being pretty useful to me, because autonomy and being in charge of your own stuff was something that I learned pretty early.
Then I think later on you get into this loop where you get positive reinforcement from being good at something. I think that's what it was with me and studying math. It's like, oh, you're really good at math. Let's take harder and harder math, and you still do well in that. I think I kept going with that up until graduate school as well.
Gaurav Ahuja
You went to Thomas Jefferson for high school. It feels like a lot of entrepreneurial people have come out of there—impressive people more generally. Outside of selecting really great kids in the first place, what is it about a high school environment that can shape so many great people?
Vlad Tenev
Thomas Jefferson was the number-one high school in the country for a long time. I think now we're number three, so still doing very, very well. But if you look at the number of entrepreneurs that have come out of there who have started big companies, you don't have a lot. It's me, it's Howard Lerman.
I think the unifying theme was that, during the dot-com boom, a network of companies started there: AOL, all the telecoms on the Dulles Corridor. So there were smart, entrepreneurial people who were working at these companies.
TJ had a really unique position, being able to take from all the counties. You get the best kids from Loudoun, the best kids from Fairfax, Prince William County. They could kind of take the cream of the crop. You had to test into it. So there was an objective, quantitative selection mechanism that I think was rare for high schools.
And we had some great teachers. Teachers from all over the country would move and want to be at that school. We had some really innovative programs that didn't exist at other schools. For example, we had a quantum physics lab. I think we were the only high school with a scanning tunneling microscope. We had a DNA science lab, so you could take DNA Science One and Two. We had genetics and a great lab director.
The faculty was really connected with local companies that were doing government research and places like NIH. When you were a senior, you could either self-direct your own research on site, or do a mentorship where, during school hours, you could go and work at a place. The end goal would be to actually produce some research. I had a mentorship at NIH, which was pretty crazy.
So I think it was a combination. They had great selection. It was a good time, with a local network that produced good kids in the top of the funnel. They capitalized on it—they saw this opportunity, got some good teachers, and put enough investment in to nurture that.
Gaurav Ahuja
You grew up with financial insecurity but also extraordinary educational opportunities. As a father, what are you trying to carry forward from that experience, and what are you not?
Vlad Tenev
It's one of those things I think about a lot, because I think it's harder to recreate the struggle. To some degree, can you simulate the struggle?
I don't think I've figured it out, to be honest. I think about this still. I want them to be really good at math. I'm still encouraging that and pushing them to do that. I care a lot about them not being wasteful. So if we buy something, do you really need it? Are you going to use it? I'm trying to teach them the value of money and the value of investing.
I think it's really about: can you take the positive things and emphasize them while adding a little bit of friction to discourage the negatives?
To some degree, you never really know. I don't know what situation I would have been in if I had grown up in Bulgaria or things had been different. I think there is some unique self-motivation that can be created in all environments.
On Physics and Financial Markets
Gaurav Ahuja
What drew you to physics when you got to college?
Vlad Tenev
I became interested around college in physics for two reasons. One, it was hard. Two, I became interested in these fundamental questions: what happened before the Big Bang? How did the universe start? What are the laws and rules?
I started reading about string theory and relativity. When I got into Stanford, I was interested in a lot of things. I had done some biotech research at NIH and had just started reading about all this physics stuff. My intent was to be a physicist. I thought that was challenging, aligned with my skills, and I loved pondering those big questions.
Gaurav Ahuja
Most people would not put the capitalistic motivations of your typical investor or entrepreneur alongside the intellectual, philosophical motivations of a physicist seeking to understand the world. How do you square those? How are those two things in one person?
Vlad Tenev
I think a lot of investors actually do. The desire to understand the world and how things work is pretty important for investors trying to understand companies and markets. It's different in some ways—you're not doing physics—but they're not altogether orthogonal. There are some amazing mathematicians who made money in the financial markets. Jim Simons, for example. There's some crossover there. I think some of the motivations can be overlapping.
They're also intellectually interesting in similar ways. When Baiju and I were in New York working on our first company, we got our hands on some of the first NVIDIA compute accelerators. At the time, they were NVIDIA Teslas, GPUs that didn't have any graphics outputs. We were looking at how we could calculate ETF basket fair values and run analysis on those.
One of the first markets for that was financial services. Some of the first developments of AI systems were in financial markets, where you have kind of perfect competition, this environment where rewards are pretty clear. So I found some overlap.
Nobody really understands how financial markets work or why we'll tend, in aggregate, to do similar things at similar times. It's almost like a law of the universe.
Gaurav Ahuja
There's a point of view where every company has a truth to it: the value of its future cash flows. Then there's another point of view, as financial markets have become larger and more institutionalized, that it's more about the actors in the system versus the truth of the system itself. Sometimes those things diverge.
How do you think about those two ways of understanding markets?
Vlad Tenev
There's a physical analogy to that too. Can you model systems from a reductionist standpoint, where you understand all the quantum phenomena and build it up that way? Or do you take a look outside in? Maybe you say, “That's too complicated. Let me model it from the outside in.”
Quantum phenomena are useful when you start looking at extremely small scales. When you look at a big scale, they're less useful, and you use completely different laws of physics. The biggest unsolved problem—the holy grail—is: can one theory define them both? People have been looking. Nobody's really solved this.
I think financial markets probably have the same question. If you're developing a high-frequency trading strategy, it's all about the actors: the orders you're placing on the order book, what your queue position is. Are you more likely to get filled with lower risk if you're at the front of the queue? Speed really matters. In those strategies, it doesn't really help to input the EPS of the company.
But if you're Warren Buffett buying Apple for the next 20 years, you don't have to know anything about hedge funds and market makers and what's happening.
There is a holy grail of financial markets, which is one algorithm to rule them all. Can you have one algorithm that takes into account all of this stuff? Can it trade extremely quickly but also make long-term bets? Can you fit those into one portfolio? I don't think anyone's solved that either, although people are much more secretive in this space.
Gaurav Ahuja
I'm curious what you think about the latest AI approaches trying to unify these worlds. And absent that approach, a lot of institutional money seems to be falling away from the Warren Buffett stock-picker strategies toward the low-volatility, systems-thinking strategies of pod shops. That could mean high-frequency algo trading or quarter-to-quarter trading from the Citadels of the world, focused on the latest secondary data.
Vlad Tenev
I haven’t seen an attempt at unifying them yet that gets me really excited. To some degree, with Robinhood we're encountering this problem, because even one individual has a couple of different time scales for their investing.
You have your retirement savings, money you expect to be around in one place for a very long time. You have bets you're making where you have conviction. Maybe a smaller portion of your portfolio is doing that. You have your children's accounts too.
The problem we're trying to solve is how to make it easy for folks to think about how much goes into each bucket. We're simultaneously trying to solve that problem and help you optimize those buckets.
Within your active trading portfolio, maybe you can use our agentic trading tools, and we can give you the information and execute it on your behalf. Even within the passive buckets, do you want to buy ETFs yourself? Do you want to use Robinhood Strategies, where we'll manage it for you? Or do you want a human advisor who can talk you through it?
We're building each of these pieces out and trying to figure out how to stitch them together into one cohesive tool that feels good to use and makes it a little more understandable.
Gaurav Ahuja
Say a system was developed, and there was enough compute in the world to perfectly predict these things. There are other people who will respond to it, and therefore there are still always opportunities.
Vlad Tenev
I think that's also a good reason why individual traders continue to exist. The more other people continue to index, the more people use the same algos, the more that opens up the opportunity for someone to go against that.
On Harmonic
Gaurav Ahuja
Given your interest in physics and understanding the world, Harmonic seems like a natural fit. Earlier in your career, what took you toward software for financial services firms rather than something like Harmonic?
Vlad Tenev
I think the time to create something like Harmonic probably was not right any time before 2023. Harmonic is the combination of two independently developing threads. One would be AI models and reasoning, which accelerated in 2023 with GPT-4, and ChatGPT before then. The other is formal verification becoming practical. That really happened with the release of the Lean 4 programming language, right around the time we started Harmonic.
I had an idea somewhat similar to Harmonic in principle when I was in college, and I was trying to recruit a few buddies into it. I wanted to create the world's largest repository of mathematical knowledge. As a math student, one problem I was running into was that all the knowledge, theorems, proofs, and techniques were in textbooks. Particularly at that time, nothing was on the internet. You ended up spending time in the library looking through abstract algebra and real analysis textbooks for theorems and techniques, with no real way to search them.
If you think about it, there's a graph of all mathematics. There are basic axioms, you put them together and get theorems, and you can build this graph of all of math. It still doesn't really exist. The closest thing is probably mathlib, which is written in Lean. But even that is not comprehensive.
A searchable repository would have solved an acute problem I had as a math student. Probably not a super commercially viable problem at the time. Not a lot of other people were interested in it.
This was before AI. I think Powerset was the big AI company at that time. The leading technology was wikis, so I created a wiki. Formal verification wasn't a thing, so you had this problem: can you semantically connect things? That was unsolved. I ended up not really pursuing it. But I think the conclusion of that first idea is something very much like Harmonic.
Gaurav Ahuja
With everything you're building at Robinhood, what made Harmonic worth taking on as well?
Vlad Tenev
Robinhood, at least thus far—and this has been changing a little with some of our recent work—was not a natural trainer of frontier models, but more a consumer of frontier models developed elsewhere.
Believe me, I'm constantly thinking about whether Robinhood should be training frontier models. But we have a lot of opportunity and a lot of other stuff to do. It's probably not the clearest route to shareholder value. At the same time, understanding how a frontier model is trained and what that entails is pretty important.
It helps Robinhood in the sense that I get to be right at the frontier and understand technical problems that are super interesting. I think it has helped Robinhood, albeit indirectly at this point.
Why is it interesting independently? Math is kind of the foundation for all reasoning. I think reasoning and math are very synonymous. If you can make a superhuman mathematician, you can solve unsolved problems in physics. You can create new knowledge.
To me as a mathematician, even solving something like the Riemann hypothesis is motivating enough to take a big swing at it, because I think that could also accelerate progress.
Gaurav Ahuja
Why did the world land on language? We've had many iterations of models, but large language models are the core of what's being used today. In an alternative universe, I could imagine a math model being the starting point. I realize everything turns multimodal eventually, but what was the sequence of events that led us to language before math? Math feels more fundamental.
Vlad Tenev
I think the main thing was that language is just more voluminous. You could get a lot of data to train on.
I think Ilya Sutskever had an interview a couple of years ago where they were saying, “These LLMs are just next-word predictors. They're not doing anything smart. It's just an algorithm predicting the next word.” I think he said something interesting: by being more intelligent, you have an advantage in being more accurate at predicting the next word.
Gaurav Ahuja
Do you think there's a natural way for Robinhood to be a customer of a math model?
Vlad Tenev
That's one of the commercial opportunities we're probing. One of Harmonic's investors was NVentures, NVIDIA's firm. The thing that I think got them excited, not speaking for them, was that formal verification has two purposes.
One that's gotten a lot of attention in the research community is math. The other is verifying software. That was actually the first commercial use case, formal verification of software and hardware.
When you're writing software, in most cases you don't really care if it's 100 percent bug-free, like if you're building a website. But in some cases it really matters, like if you're building a lunar lander or a chip.
If you’re a semiconductor maker making a chip, it’s very expensive to catch errors after tape-out. Companies hire verification teams that create a model of the chip and prove properties like liveness.
It's becoming more popular in crypto now, where you have all these smart-contract hacks. People have started formally verifying smart contracts to prove deterministically that there's no double spend, that they conserve assets, that there's no way to drain the vault.
Solana has been pretty early to this. They announced a program where the Solana Foundation will fund formal verification costs for startups, because they're smart. Probably Robinhood Chain should do the same thing.
Robinhood is a huge crypto verification and auditing customer. If Harmonic becomes the default verification layer for software and hardware, including crypto, and if there's a better mousetrap there, I think that's one area of significant overlap.
On Navigating GameStop
Gaurav Ahuja
You’ve talked about the GameStop moment quite a lot. A question you probably don’t get asked enough is, how did you raise $3.4 billion overnight? What did you have to do with investors? Was it hard to convince people? How much explanation did it take?
Vlad Tenev
It was complicated, for sure. A lot of credit goes to investors who had been along with us for the journey. Micky Malka basically committed half a billion to me with a phone call, on the spot. He's like, “I've got it. Count me in. Tell me how much more you need.”
We had to do a couple of things simultaneously. We had to raise the capital. Who knows? I think maybe we would have been okay if we hadn't raised capital, but we didn't want to take the chance.
We saw how bad the restrictions were. If we had to keep them live for multiple more days, even if we were able to maintain solvency and liquidity technically, would our brand be destroyed?
We were also worried about all of our counterparties. We rely on banks that give us lines of credit. In these situations, if some of them sniff that the company is weak or there might be an issue, they all pull their lines of credit simultaneously. We were really trying to avoid contagion.
We had to calm people down and say, “Actually, we're in strong regulatory standing. This is a one-time, weird technical issue. Customer funds are safe.” It was a lot of education about what was actually happening. What are clearinghouse deposits? Why do you have to use corporate cash?
A lot had to do with early investors like Micky being able to make strong commitments early on. If it had been many hours or days, and we were out there trying to raise money but nobody was providing it, it would have been a challenging situation.
The one thing we did that I think ended up being critical—even though we got a lot of grief for it—was that restricting buying in certain securities kept the problem from escalating. That ultimately meant our destiny was in our hands. But it was like the fog of war.
There was a lot of uncertainty, and we had to execute on what we thought was most important: keep the system stable. The engineering team did a great job making sure that, with all the restrictions, people were able to close their positions and manage their risk.
I was out there raising money with Jason and Shiv. The comms team was working on how to talk to customers and all our stakeholders. It was all hands on deck through the weekend.
On Earning Investor Trust
Gaurav Ahuja
That deep relationship with Micky and Ribbit was incredibly impactful in a tough moment. They're still investors, but you have a totally different class of investors now in the public markets. Your board isn't necessarily just your investors anymore.
Do you have that same close relationship with investors? Are you even able to have it in public markets, where people can be shorting you at any moment?
Vlad Tenev
It's very different. I also felt this with every additional round of financing when we were private. We had some great partners, but it always felt like they didn't know the business as well as my co-founder and I, who were already there.
I always had this feeling that we were proving ourselves to this new investor. Maybe they were second-guessing the investment: “Was my money well spent here?” Or, “Shit, do they have some buyer's remorse?”
For all rounds, there was an initial period where we had to prove ourselves. Over time, we were able to show our new investors that we knew what we were doing. We made good decisions, we delivered. In some cases that was pretty quick. In others it took longer.
With the IPO, it was the same thing. We had this new class of public-market investors. They hadn't seen us operate. They didn't know us. It's not like Micky, who's been following the company. Micky can tell them, “These guys are actually great,” but until we deliver in this new context, are they going to believe it?
I think it took about three years from when we went public before I felt we'd proven ourselves in the public markets. That seems like a long time in hindsight, but it could have been 10 years.
For a while in the doldrums of 2022, it felt pretty bad. If you'd gone to Vlad at a $6 Robinhood share price and told him, “In 10 years, you might be at $60,” maybe I would have been like, “I'll take that.” Ten times in 10 years seems pretty good.
What surprised me was that, when we got the trust of the public markets, it happened really quickly. It was like 10 times within less than a year.
And there was one time, actually—I think it was the end of 2023. I was in London, and we had just launched in the UK. It was a time when I felt really good things were happening. In 2022, I felt shitty. A lot of work needed to be done before I could start feeling good about the business.
But in 2023 we had turned GAAP profitable. We were launching in the UK, so we were doing new stuff. We had acquired X1, and the credit card was coming. Good things were happening, and I felt good, but the stock was still low.
I had a pretty tough meeting with an investor who said, “Tell me why I shouldn't dump all my stock. Do you really want to keep running this company?” The subtext was, “Should you step down and hand it over to someone else?”
At that time, a lot of founders just didn't make it through that period, unfortunately.
I was at the point where I felt really good. Things were firing again. Maybe you didn't see it in the stock, but it felt different. My thought was: maybe public investors will never get it. We'll have to do this the good old-fashioned way of increasing our revenue and profit and buying back our stock, which we did.
It didn't take too long after that. That was a tough conversation, but this investor ended up not selling and did very well.
On Opening Private Markets
Gaurav Ahuja
That brings me to Robinhood Ventures. In the early days, you were talking to pre-IPO companies about being public versus private. Part of the pushback was: “If I wanted to be in the public eye, I'd be a public company. I'm not ready for that.” I remember this distinctly on the Cheeky Pint podcast with John Collison.
How has that narrative shifted? How have you convinced founders of these great companies to be part of Robinhood Ventures?
Vlad Tenev
A big part of this is persistence. This is one of those problems that's a decreasing headwind. The longer we're operating, the more Robinhood Ventures continues to grow, the more companies people see being part of it, the easier it gets for subsequent ones.
With Robinhood Ventures Fund, time has made it easier to get into great deals.
For Robinhood Ventures Fund II, which is seed and early-stage investing, our experience is that the hit rate for getting into deals is much higher. That's for a couple of reasons. One, it's not as systematized. When you're a late-stage company, you have a finance team. Finance teams tend to be conservative, because what you really don't want is to screw something up by doing something weird.
At the early stage, it's just the founders, and they need capital. We're an investor like everyone else. The ability to get into those deals has been super easy.
I think we've changed the industry for the better. I want to get to a place where it would be an anomaly not to have individual investors on your seed and Series A cap table. That's the logical end state.
If we get pre-IPO, ultra-late-stage companies to embrace retail, and seed-stage companies too, the middle takes care of itself. I don't think anyone else is really doing this. I'm sure they're going to try now, but probably after we've established ourselves as a clear leader. I think it'll be good for our business.
On Expanding Beyond Brokerage
Gaurav Ahuja
Speaking of the Robinhood ecosystem, one thing I get excited about is where some of these products can cross over. With Rothera, what are uniquely Robinhood ideas you can do coupled with your other products?
Vlad Tenev
We're continuing to innovate with prediction markets. There are areas where you trade a stock and want prediction markets around that stock. A great example would be EPS and revenue contracts, where maybe I want to trade around earnings.
Sometimes I can have a thesis that Tesla is going to beat EPS or deliveries, and for some other reason—forward guidance or whatever—the stock goes down anyway. Prediction markets, or prediction-market-like products, can help you hedge out that exposure and more specifically place that trade.
There's always been an open question of how sports fits in, and I don't think we've figured it out. We call it the super-app enigma. A lot of people want things in one place, but if you want a front-and-center sports prediction markets experience, you might want it to be your front page.
We've also gotten feedback that some people just don't like it next to their retirement. We have to figure out how to navigate that through a suite of apps or personalization, probably a combination of both.
We've had to deal with that on the banking side too, in another context. We've tried getting banking and spending into the Robinhood app for many years: cash management, checking and savings. It never quite hit until we rolled out the separate banking app. We'd hear a lot of, “I don't really like my banking and my trading in the same lane.”
Gaurav Ahuja
Separating the apps actually increased usage and sign-ups?
Vlad Tenev
That was the point at which the product hit product-market fit. We were able to be more creative with the design than we could if constrained by the super app.
We get this criticism now about Robinhood Chain: is it an RWA chain or a meme chain? These two things complement each other. You see the enthusiasm around Robinhood Chain right now. A lot of it's born of memes, but we've got all these developers and market makers integrating with it. You see that enthusiasm spilling over into developers trying cool stuff with real-world assets.
I think you're seeing the same thing with prediction markets. Before elections, before sports, nobody was really trading prediction markets. It took sports and elections to make it a big category and draw attention.
Now the critical part will be: can we turn that liquidity, attention, and retail usage into interesting products that might not have been easily bootstrapped without it?
On Lessons from Crisis
Gaurav Ahuja
There are a lot of times when you could have looked at Robinhood from the outside and said it would die. In the early days, you were the zero-fee app, and every investor probably asked, “Won't the incumbents do this too?” Sure enough, they did.
Then there's GameStop, the stock going down 90 percent, SBF owning seven percent of your company and the uncertainty around that. There will be more moments in the future. What has been forged into the company as a result of these near-death experiences—or optically near-death experiences—that you carry forward?
Vlad Tenev
Those were challenging times. I had all sorts of stress responses, and psychologically there were ups and downs for sure. But now, looking back, those are memories I cherish.
It's like the hero's journey. Do you want to read the story of a company that succeeded, never made mistakes, and was gradually up and to the right? Or are those dramatic, tense moments where the magic is?
I look back personally and think, “Those were awesome experiences. I'm so lucky to have lived that.”
Then there was GameStop, and a movie with Sebastian Stan playing me. I’m sure they would have loved Robinhood to fail so the end card could say that two years later Robinhood filed for bankruptcy. Instead, they had to say Robinhood had the worst IPO of a company of its size ever. And I’m laughing about that, like, “When’s the sequel coming?”
My only regret was that I didn't enjoy it more at the time. I've learned to take myself and the outcome out of it a little, and understand that in the future I'll probably appreciate having gone through it. Maybe that means I should enjoy it a little more at the time.
I think that's made it easier to go through crises. It's almost a religious way to look at things: you can think of an obstacle as a problem, or the obstacle itself is a path. It helps you grow, and you have to go through it. It's either holding you back or helping you reach the next level. In hindsight, it's been the latter.
Gaurav Ahuja
We talked earlier about emotional modulation starting when you were young, with your first investment losses. To 12-year-old you, that was probably the biggest thing that had happened. Fast-forward, and the modulations get bigger and bigger.
If I'm reading between the lines, in these moments there's a feeling of, “Will I make it after this? Will the company make it?” Increasingly, the strength of the company, the cash and cash flow you have, probably also implies, “Whatever crisis comes, we can be here tomorrow.” You can step back and say you'll appreciate the moment in the future.
Vlad Tenev
Yes, but you can also take bigger and bigger risks. Now there are more chips on the table. You can make the same bets and have more security, but you can also go all in with a larger amount. That's exciting too. I want to at least reserve the right to make those bets.
There are two sides: you feel more secure, but there's also that wolf in you that realizes you can take bigger and bigger risks.
On Ambition and Retirement
Gaurav Ahuja
Do you ever imagine a point where you're ready to step away from Robinhood? What do you think that moment would feel like?
Vlad Tenev
I've thought about this question. There's a story about Alexander the Great weeping because there were no more lands left to conquer. That's what I would like my retirement to be, if there ever is one: a sad affair because there's nothing more left to conquer.
But then I think, is that possible? Maybe that's why I'll never retire, because you'll never get to that point. There's always going to be more to do.
I sometimes think about taking a really nice, long vacation where I don’t have to worry about looking at my phone.
I’ve never really had a vacation. I went straight from high school to college, college to grad school, dropped out of grad school to start my first company. But then I also think, well, if I go on a short vacation, I get pretty bored after two days. So maybe a long one would actually be horrible.
The opinions expressed in this newsletter are my own, subject to change without notice, and do not necessarily reflect those of Timeless Partners, LLC (“Timeless Partners”). More...
Nothing in this newsletter should be interpreted as investment advice, research, or valuation judgment. This newsletter is not intended to, and does not, relate specifically to any investment strategy or product that Timeless Partners offers. Any strategy discussed herein may be unsuitable for investors depending on their specific objectives and situation. Investing involves risk and there can be no assurance that an investment strategy will be successful. Links to external websites are for convenience only. Neither I, nor Timeless Partners, is responsible for the content or use of such sites. Information provided herein, including any projections or forward-looking statements, targets, forecasts, or expectations, is only current as of the publication date and may become outdated due to subsequent events. The accuracy, completeness, or timeliness of the information cannot be guaranteed, and neither I, nor Timeless Partners, assume any duty to update this newsletter. Actual events or outcomes may differ significantly from those contemplated herein. It should not be assumed that either I or Timeless Partners has made or will make investment recommendations in the future that are consistent with the views expressed herein. We may make investment recommendations, hold positions, or engage in transactions that are inconsistent with the information and views expressed herein. Moreover, it should not be assumed that any security, instrument, or company identified in the newsletter is a current, past, or potential portfolio holding of mine or of Timeless Partners, and no recommendation is made as to the purchase, sale, or other action with respect to such security, instrument, or company. Neither I, nor Timeless Partners, make any representation or warranty, express or implied, as to the accuracy, completeness or fairness of the information contained in this newsletter and no responsibility or liability is accepted for any such information. By accessing this newsletter, the reader acknowledges its understanding and acceptance of the foregoing statement.